A secured deepwater industrial hub on the Strait of Malacca, and a sovereign advanced-manufacturing flagship in Abu Dhabi. Move forward to take them in order, or select one to begin. Hover any underlined figure for its source.
I · MALAYSIA — SLIDES 02–18
Malacca Strait Hub
3,000 acres of royal-granted land at Port Dickson. Port, bunkering, refining, city and renewables on one master plan — with a live map of the corridor.
II · ABU DHABI — SLIDES 19–33
TAU
The insulated conductor, made designable. Three horizons, named OEM qualifications and real line economics — with a live capacity model.
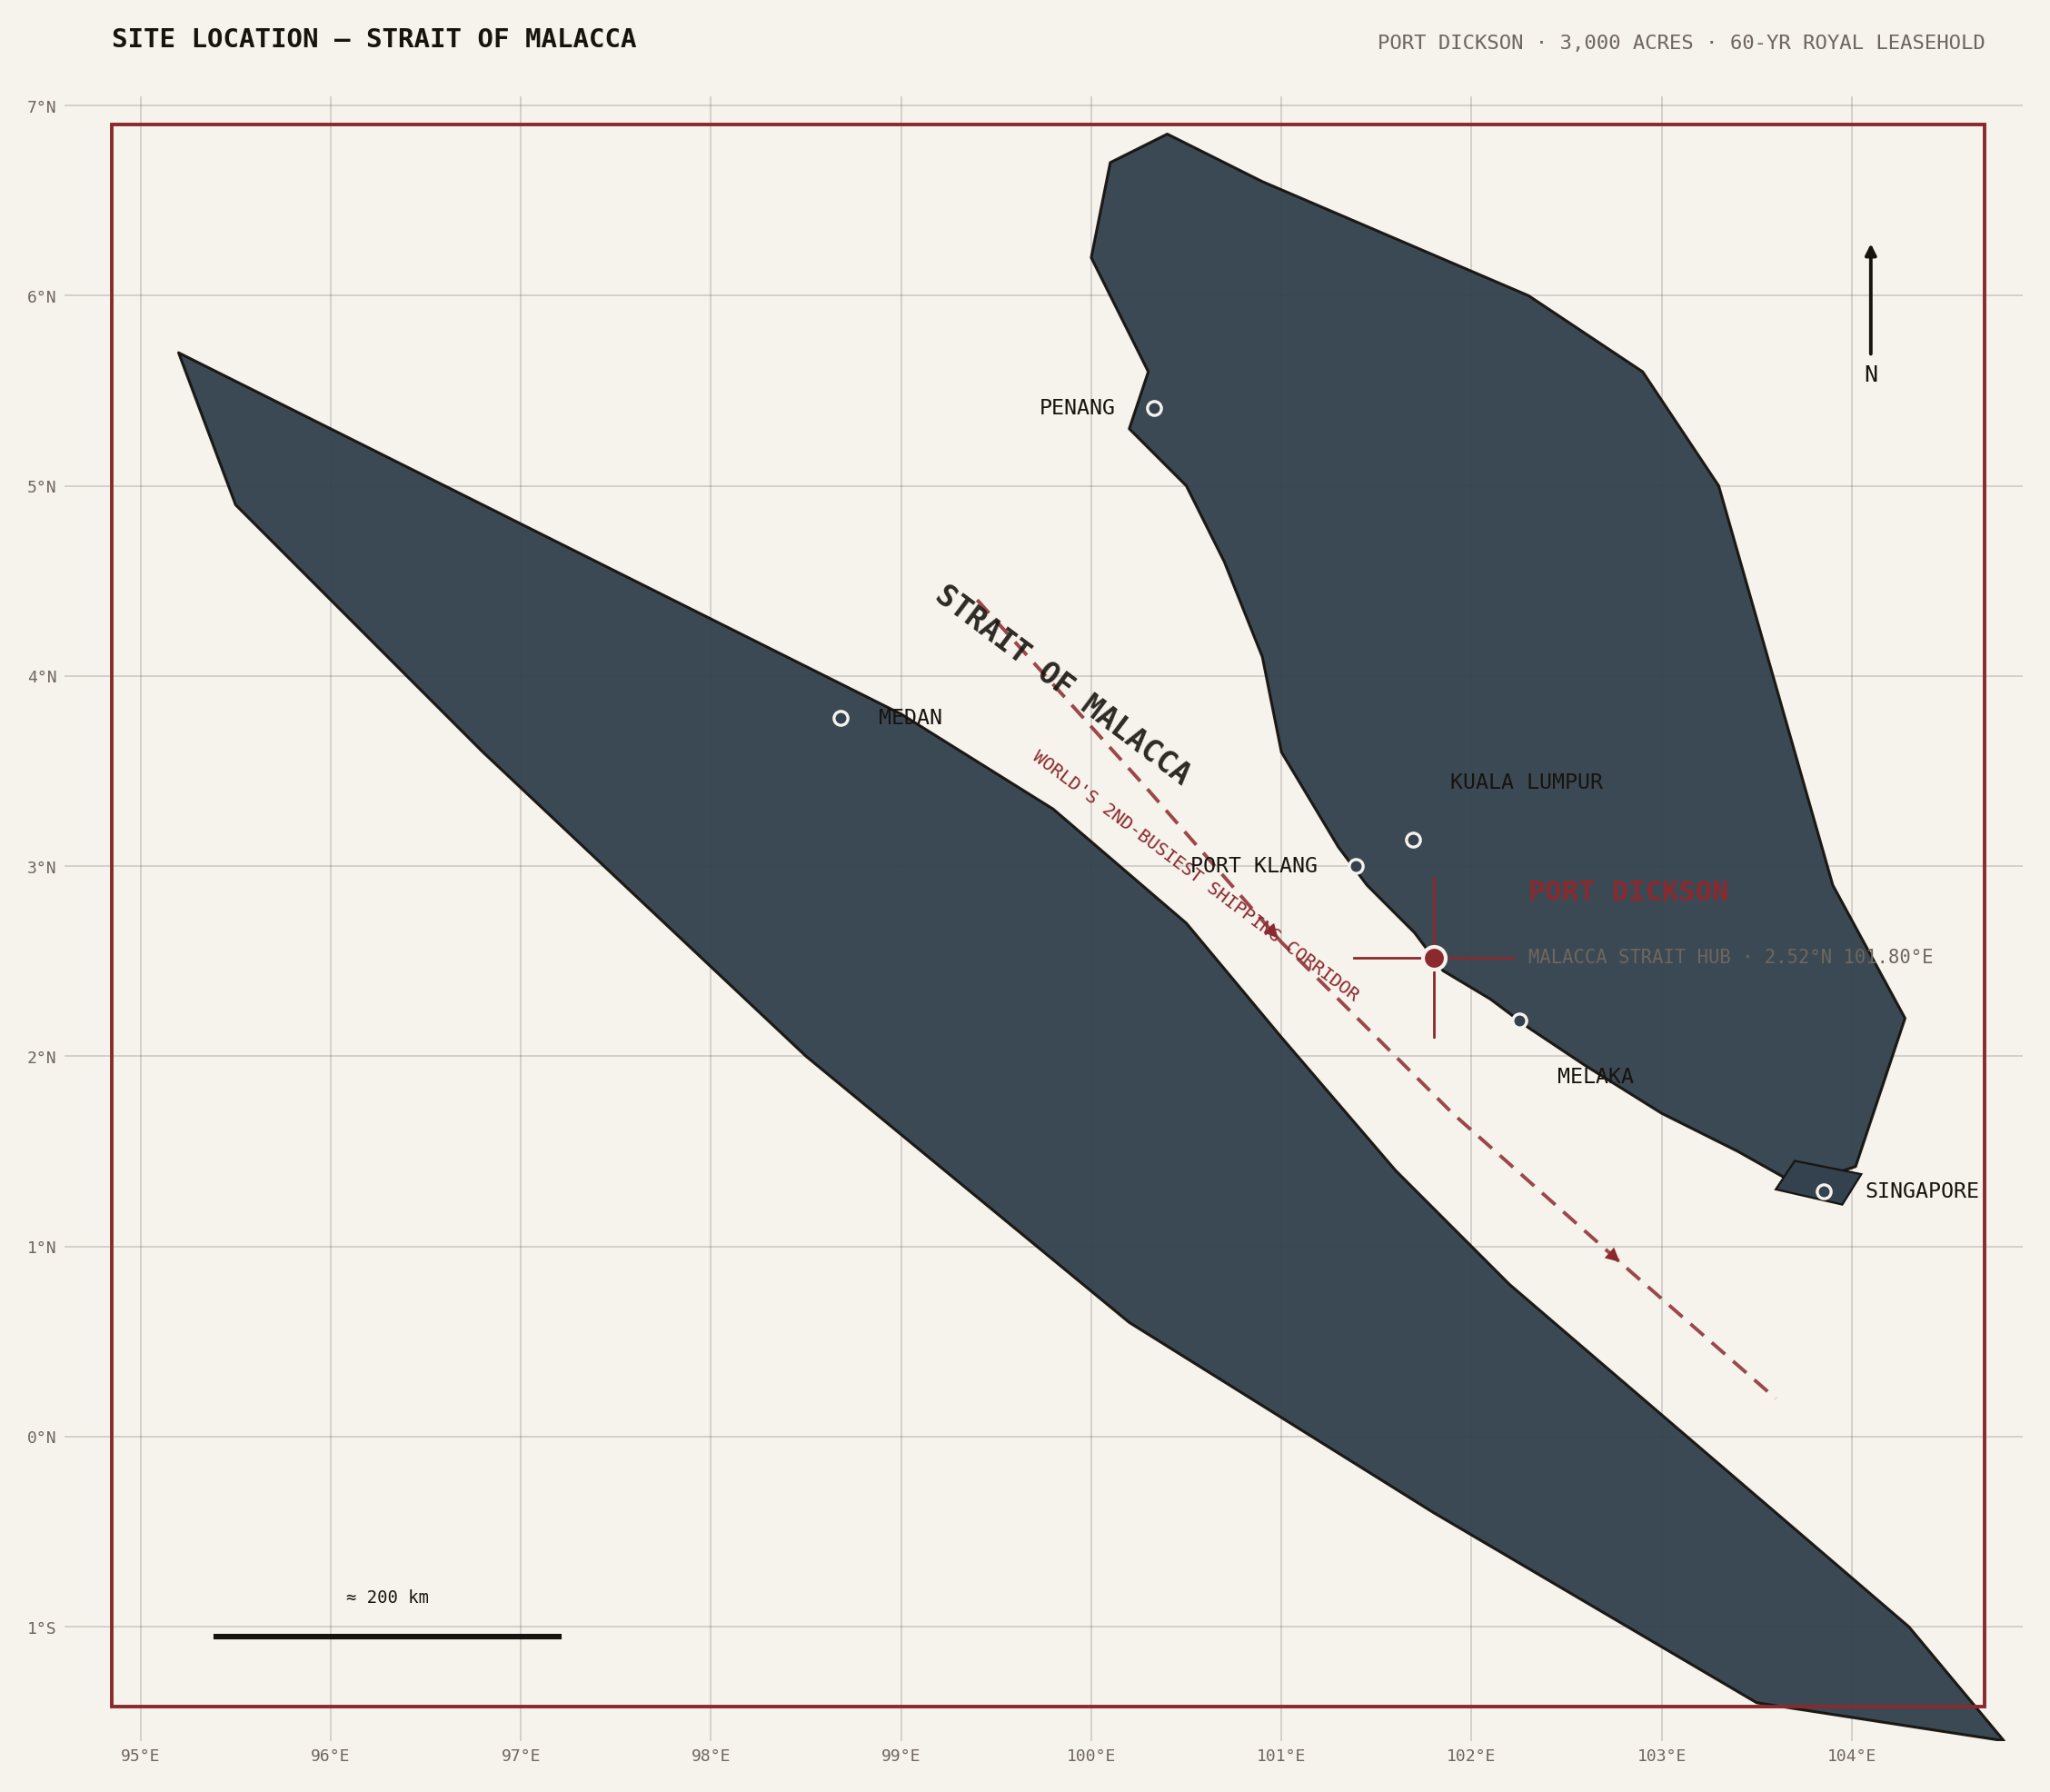
02°31′N 101°48′E
Three thousand acres of secured coastline on the world's second-busiest shipping lane.
3,000
ACRES
60 yrs
ROYAL LEASEHOLD
5
VERTICALS
MYR 2.5B
PROGRAMME, MID-CASE
A Briefing to Her Highness
Malacca Strait Hub
02°31′N 101°48′E · PORT DICKSON, MALAYSIA PRELIMINARY — SUBJECT TO INDEPENDENT VALIDATION STRICTLY PRIVATE & CONFIDENTIAL
The Vision
02°31′N 101°48′E
A landmark of trade, industry and enterprise on the Strait of Malacca.
HOW THE 3,000 ACRES ARE SET OUT
Energy & industrial1,400 ac
Port & logistics700 ac
Urban & coastal400 ac
Buffer & green300 ac
Common infrastructure200 ac
STRICTLY PRIVATE & CONFIDENTIALMALACCA STRAIT HUB
The Royal Mandate
GRANTED, NOT BID FOR
A mandate held under royal grant.
14 MAY 25
Letter of Appointment issued, naming Forfait as the appointed representative facilitating investment into the hub.
CUSTODY
Her Highness and the Undang of Luak Johol stand as custodian of the land and partner to the undertaking.
PRINCIPAL
Eng. Mazen Ali Awadh Jaber, for Forfait Representation of Companies, Abu Dhabi.
THE INSTRUMENT — ON THE RECORD
INSTRUMENTLetter of Appointment
DATED14 May 2025
CUSTODIANHer Highness · the Undang of Luak Johol
REPRESENTATIVEForfait, facilitating investment
LAND3,000 acres, Port Dickson
TENURE60-year renewable royal leasehold
No concession bidding. No acquisition risk.
STRICTLY PRIVATE & CONFIDENTIAL02°31′N 101°48′E
How It Came Together
TWO PROPOSALS, ONE SITE
A refinery and a port were proposed apart. Y.T.M. brought them together.
ORIGINALLY PROPOSED
Refinery — Kelantan
East coast. No deepwater container frontage, no bunkering demand at the gate.
ORIGINALLY PROPOSED
Port — Seremban
Inland of the corridor. Throughput without a fuel business behind it.
→
MERGED BY Y.T.M. — NEGERI SEMBILAN
One site on the Strait, carrying both.
The refinery feeds the bunkering terminal; the bunkering terminal serves the transits the port already attracts. Neither business has to be built on its own economics — and both sit on land the state already controls.
THIS MERGER IS WHY THE HUB IS FIVE VERTICALS ON ONE MASTER PLAN RATHER THAN FIVE SEPARATE PROJECTS.
STRICTLY PRIVATE & CONFIDENTIAL02°31′N 101°48′E
The Opportunity
HOVER ANY FIGURE FOR ITS SOURCE
The world's busiest waters, served by terminals that are running out of room.
40%
of global seaborne trade passes the Strait
25%
of the world's seaborne oil
120,000+
vessel transits a year
3–4%
annual container demand growth to 2035
Singapore's terminals are consolidating near capacity and Port Klang is congested. That is a durable opening for a modern, deepwater, ESG-aligned hub on secured land, under one master developer.
STRICTLY PRIVATE & CONFIDENTIAL02°31′N 101°48′E
The Secured Asset
3,000 ACRES · ROYAL GRANT · LAND VALUE > MYR 2.6B
Port Dickson. VLCC-ready frontage at 18 m draft.
Granted by Y.T.M. Dato Johan, Undang of Luak Johol — perfected as a 99-year registered leasehold under the National Land Code 1965.
MASTER PLAN — THREE ZONES, SEQUENTIAL ROLLOUT
Core Industrial1,000 ac
Port, bunkering, refinery, tank farms
Utility & Logistics Buffer1,000 ac
Warehousing, storage, customs, O&M
Mixed-Use & ESG District1,000 ac
Residential, commercial, renewables
STRICTLY PRIVATE & CONFIDENTIAL02°31′N 101°48′E
The Corridor — Who Already Earns From This Water
CORRIDOR PORTS · 2025 THROUGHPUT
Singapore44.66M TEU
Port Klang15.14M TEU
Tanjung Pelepas14.03M TEU
Penang (indicative)1.50M TEU
Malacca Strait Hub · Phase 33.00M TEU
0
VESSEL TRANSITS A YEAR
0M TEU
HANDLED BY CORRIDOR PORTS · 2025
USD 0B
BUNKER FUEL SOLD AT SINGAPORE · 2025
WHAT MSH NEEDS TO TAKE
4.0%
OF CORRIDOR TEU
8.8%
OF SINGAPORE BUNKERS
The case does not require the corridor to grow. It requires a small share of what already passes the site.
HOVER ANY MARKER · SOURCES: MPA SINGAPORE · MOT MALAYSIA · MMC PORT · SHIP & BUNKER — FULL-YEAR 2025STRICTLY PRIVATE & CONFIDENTIAL
What We Are Building
SELECT A VERTICAL
Deepwater port
2.5–3.0M TEU/YR
Marine bunkering
5M TONNES/YR
Modular refinery
10,000 BPD
Coastal city
3,000 UNITS
Biomass & solar
30 MW
STRICTLY PRIVATE & CONFIDENTIAL02°31′N 101°48′E
The Market & Demand
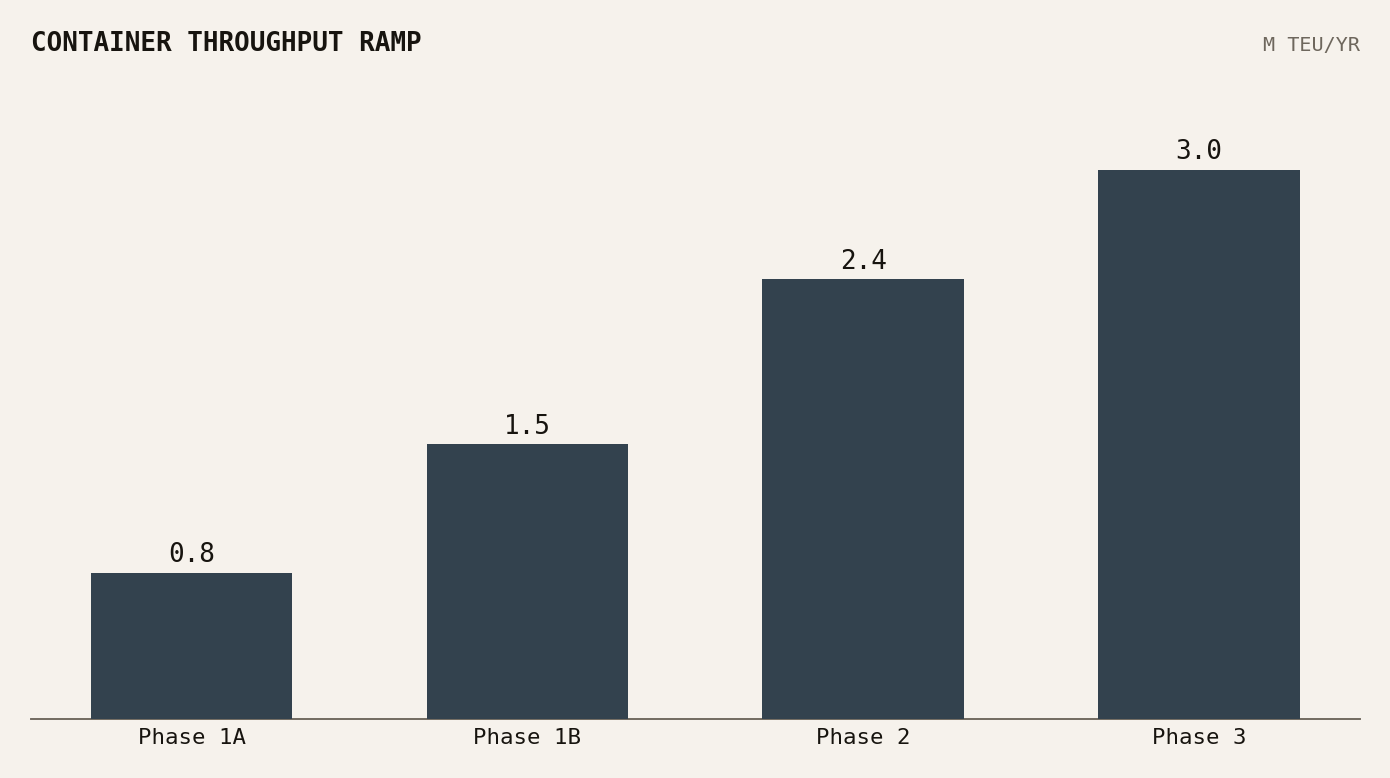
0.8 → 3.0 M TEU ACROSS PHASES 1A–3
A deliberately conservative ramp — capacity phased behind demand, never ahead of it.
Each vertical is pulled by a constraint someone else already has.
SEGMENTMARKET DRIVERMSH OPPORTUNITY
MaritimeSingapore and Port Klang projected to saturate by 2027–28; TEU rerouting begins2.5–3.0M TEU a year from regional overflow, within five years of operation
BunkeringSingapore supplies over 90% of ASEAN marine fuel — a single point of concentration10–15% regional share, equal to 6–9M tonnes a year
RefiningIMO 2020 fuels, regional diesel shortfalls met by imports10,000 BPD modular plant — MYR 1.2B a year in EN590 diesel
Real estateUrban spillover from the Klang Valley, and coastal tourism2,000 residential and 1,000 commercial units by 2035
Energy & ESGNet Zero 2050, and access to green finance30 MW biomass, grid sale, carbon credits
Negeri Sembilan StateInfrastructure and incentives — preliminary discussions
LICENSING PATHWAY
EIA — Environmental Quality Act 1974
Port licence — Port Authorities Act 1963
Grid licence — Energy Commission, ESA 1990
Bunkering — IMO 2020 & MARPOL Annex VI
MIDA Pioneer Status & GreenTech incentives
DISPUTES GO TO THE AIAC, KUALA LUMPUR — AWARD FINAL.
STRICTLY PRIVATE & CONFIDENTIAL02°31′N 101°48′E
Built to International Standard
DESIGN CODES & GLOBAL BENCHMARKS
Designed against the codes the world's great ports are already built to.
CODES & STANDARDS
PIANC
BS 6349
API 650/620
NFPA 30
ASME
IMO 2020
FIDIC
IFC PERFORMANCE STANDARDS
EQUATOR PRINCIPLES
BENCHMARKED AGAINST
Maasvlakte 2ROTTERDAM
TuasSINGAPORE
Jebel Ali & KhalifaUAE
Pengerang RAPIDMALAYSIA
Fujairah · Duqm · JazanGULF
STRICTLY PRIVATE & CONFIDENTIAL02°31′N 101°48′E
The Capital Plan
MYR 2.5B (~USD 532M) · THREE PHASES · 10% CONTINGENCY EACH
CAPEX BY CATEGORY — MYR MILLION
CATEGORYPH 1PH 2PH 3TOTAL
EPC / construction412.5605.0357.51,375.0
Engineering & design75.0110.065.0250.0
Utilities & access infra90.0132.078.0300.0
Consulting / ESG / PMO60.088.052.0200.0
Permitting & legal37.555.032.5125.0
Contingency & escrow75.0110.065.0250.0
Total per phase7501,1006502,500
PHASING — SELECT
Phase 1
2026–28
Phase 2
2027–29
Phase 3
2029–32
EPC AT 55% SITS INSIDE THE 50–65% BAND OBSERVED IN SOUTHEAST ASIAN AND MENA PORT-ENERGY DEVELOPMENTS.
STRICTLY PRIVATE & CONFIDENTIAL02°31′N 101°48′E
Returns, and Resilience
BASE CASE · NPV AT AN 8% DISCOUNT RATE
13.2%
BLENDED PROJECT IRR
7–8 yrs
PAYBACK PERIOD
1.6–2.1B
NPV · MYR @ 8%
45–52%
EBITDA MARGIN
60 : 40
TARGET DEBT TO EQUITY
25-YEAR GROSS REVENUE BY STREAM — MYR
BunkeringMYR 3.5–4.0B
6–9M MT marine fuel throughput
Real estateMYR 3.5–3.8B
Residential, commercial, tourism and leasing
RefiningMYR 1.2–1.5B
Modular plant — low-sulfur and specialty fuels
Port operationsMYR 0.5–0.7B
TEU handling, berthing fees, storage
Biomass energyMYR 0.2–0.3B
Grid sale, carbon credits, industrial users
SENSITIVITIES CARRIED IN THE BASE CASE
Fuel pricing modelled at ±20%
TEU capture held to 2.5M by Year 5
Real estate absorbed over a 10-year cycle
Biomass at 85% uptime, 80% offtake guaranteed
Five streams, five different demand drivers. Bunkering and real estate each carry roughly a third of the 25-year revenue — neither depends on the other.
The immediate move is to commission the independent Bankable Feasibility Study — the step that turns a well-founded plan into an evidenced one, and the natural next act of the mandate.
01
A cornerstone partner to anchor Phase 1 — port and bunkering
02
Phase 1 capital of MYR 750M (~USD 160M) within the MYR 2.5B programme
03
Support to commission the independent Bankable Feasibility Study
STRICTLY PRIVATE & CONFIDENTIAL · PRELIMINARY — FIGURES SUBJECT TO INDEPENDENT VALIDATION, INCLUDING A BANKABLE FEASIBILITY STUDY
FORFAIT REPRESENTATION OF COMPANIES — SOLE PROPRIETORSHIP LLC, ABU DHABI (CN-2010083) · DATA HANDLED UNDER THE UAE PDPL (FEDERAL DECREE-LAW NO. 45 OF 2021)
Part Two
From a coastline to a conductor.
The first briefing concerned a place. The second concerns a component — one that sits beneath every electric machine, and beneath the electrified economy itself.
Polymer fused directly onto the conductor, in a single pass.
The conventional line dips and bakes thirty to fifty times to reach the same build. Commodity PEEK extrusion tubes a thick 100–200 µm layer over the conductor; TAU fuses at a 30 µm minimum and holds ±2 µm — then adds the asymmetry and length-wise variation a fixed die cannot produce.
THE DRYCYCLE® LINE — ONE PASS
01
Bare conductor in — round, flat or hollow
02
Dry fusion — polymer fused directly onto the metal, no solvent
03
Measured in-line, then wound — 30 µm at ±2 µm
30 µm
builds held to ±2 microns
1,000 V+
and 260 °C, on space-grade PEEK / PFA / TPI
Zero
solvent — recyclable by design
−50%
cost of transformation vs the incumbent route [CO]
BUILDS FROM 30 TO 400 µm, CONCENTRIC OR ECCENTRIC · ROUND 0.7–8 mm, FLAT OR HOLLOW 1.5–50 mm² · PEEK, PEKK, PPS, PPSU, TPI, PFA, PA11/12 ON COPPER, ALUMINIUM, NICKEL-PLATED OR SILVER. STRICTLY PRIVATE & CONFIDENTIAL — PRINCIPAL'S COPY · THE HOUSE REPRESENTS; IT DOES NOT CERTIFY.
Why It Matters Now
HOVER ANY FIGURE FOR ITS SOURCE
Above roughly 800 volts, the century-old insulation envelope ends.
400–500 V — PD IGNITES
800 V — PENALISED
1,000 V+
Electric vehicles
Renewables
Transformers
AI data centres
All four are being pushed through that ceiling at the same time. Whoever makes the insulation gap programmable holds a position beneath the whole electrified economy.
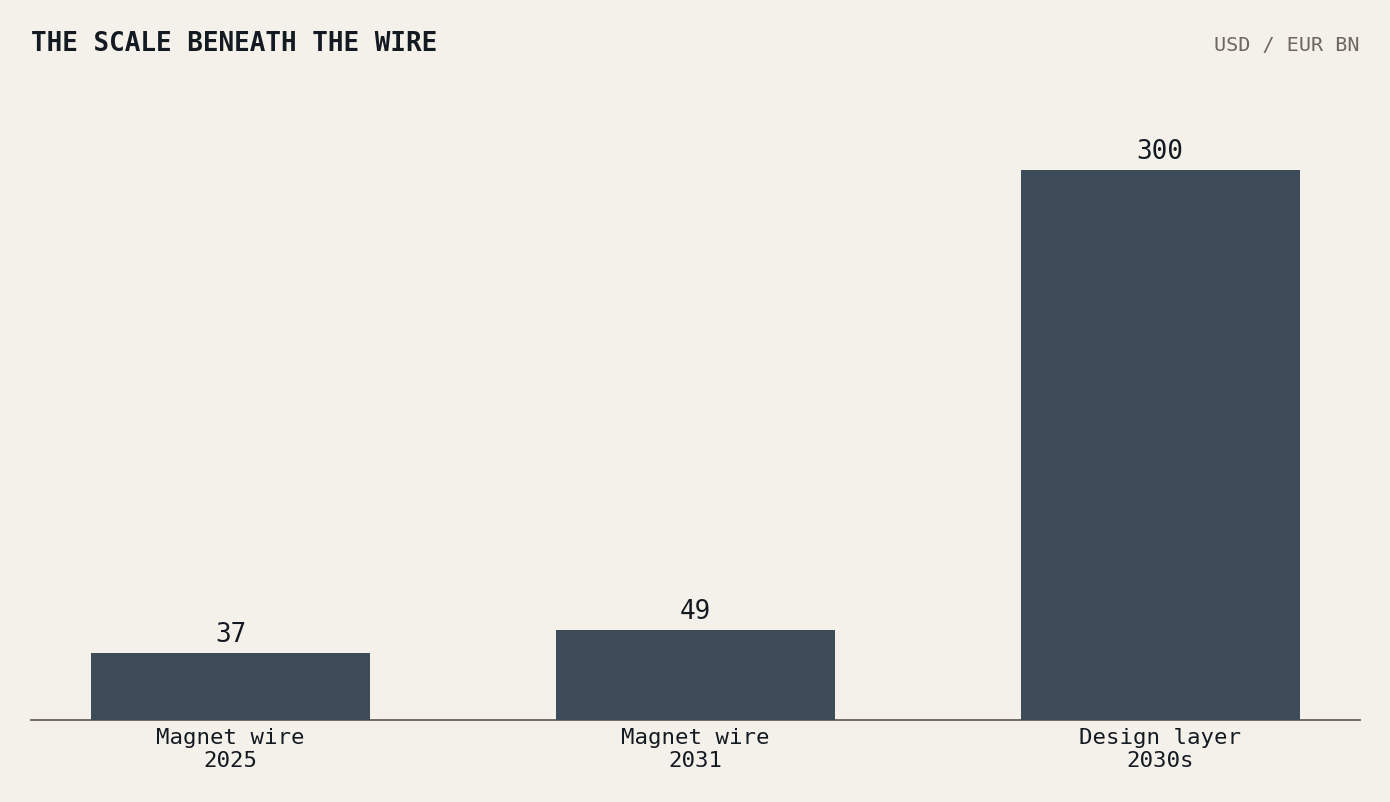
The same conductor is the design layer beneath a far larger addressable market — €300B+ by the early 2030s once motors, transformers, RF and aerospace are counted.
Enamelled insulation is still ~94% of magnet-wire sales today. The entire incumbent base is the switching opportunity.
MARKET FIGURES CITED · COMPANY FIGURES FOR DILIGENCESTRICTLY PRIVATE & CONFIDENTIAL
MOVE THE SLIDERS · HOVER ANY FIGURE FOR ITS SOURCE
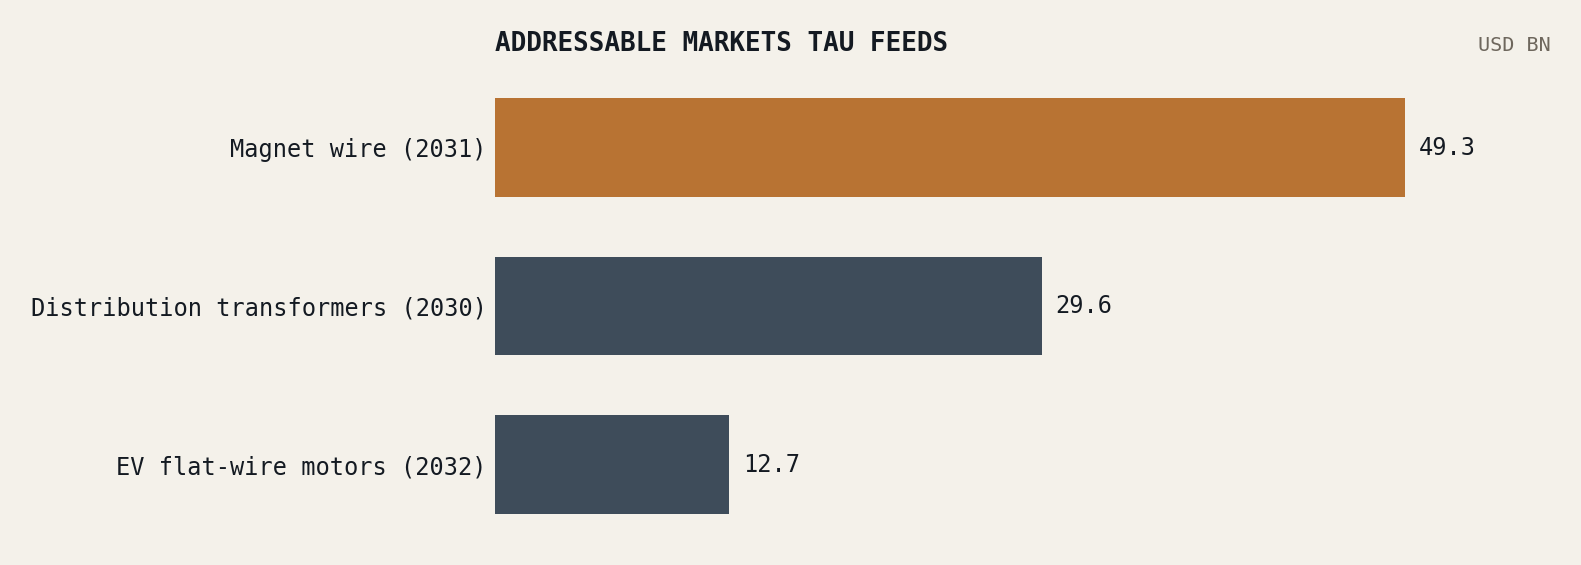
TAU'S SHARE OF THE 2031 MAGNET-WIRE MARKET — USD 49.27B
0.23%
ONE PART IN 435 — THE FLAGSHIP DOES NOT NEED SHARE; IT NEEDS THE LAYER.
CAPACITY MODEL — TAU LINE ECONOMICS [CO]
LINES8
t / LINE / YR750
€k / TONNE17.5
6,000 t
OUTPUT
€105M
REVENUE
0.44%
WIRE SHARE
€16M
EBITDA
COPPER: ICSG WORLD COPPER FACTBOOK 2025 (27.4 Mt REFINED USE, 2024) · MAGNET WIRE: MORDOR INTELLIGENCE. CAPACITY, YIELD AND PRICE ARE OPERATOR INPUTS FOR DILIGENCE [CO] — NOT COMPANY GUIDANCE.
RUN FLAT OUT, THE FLAGSHIP STILL TAKES A SLIVER OF THE WIRE MARKET — THE VALUE IS NOT VOLUME, IT IS OWNING THE LAYER THE VOLUME MUST PASS THROUGH. STRICTLY PRIVATE & CONFIDENTIAL — PRINCIPAL'S COPY.
The ESG Inversion
REGULATION AS ADVANTAGE
THE INCUMBENT PROCESS
Solvent enamelling emits VOCs and cannot be recycled.
Under tightening net-zero and scope-3 regimes, both become liabilities exactly as demand scales.
TAU
Solvent-free and recyclable, by construction.
On TAU's account, a genuinely low-carbon, recyclable motor-wire footprint can only come from a solvent-free process [CO] — turning regulation from a cost into an advantage.
The rules that tighten around the industry are the rules that clear TAU's path.
AUTOMOTIVE QUALIFICATION RUNS 18+ MONTHS FROM FIRST SAMPLES TO SERIES PRODUCTION. THE GATES ABOVE ARE THE INDUSTRY'S OWN.
THE MARQUEE PROGRAMME
Aston Martin Valhalla
TAU was chosen to power Aston Martin's most exclusive electric supercar — face-by-face engineered asymmetric wire, delivered at production quantity.
CHOSEN OVER DOMESTIC GIANTS THAT ALREADY CARRIED PEEK PRODUCTS IN THEIR CATALOGUES.
STRICTLY PRIVATE & CONFIDENTIAL — PRINCIPAL'S COPYTHE HOUSE REPRESENTS; IT DOES NOT CERTIFY
The Economics of One Line
[CO] COMPANY FIGURES — PER MODULAR DRYCYCLE® LINE
The unit of growth is a line, and a line pays for itself in about six months.
~750 t
capacity per line, at a 90% load factor
~€850k
capex per line, plant included
€2M+
EBITDA per line per year at scale
~6 mo
capex payback
PRICE STRUCTURE PER TONNE OF FINISHED WIRE
All-in selling price~€17,500 / t
of which copper, passed through at LME~66%
Transformation price — the value added~€5,900 / t
Contribution profit~€3,000 / t · 50%+ MARGIN
RETURN ON CAPITAL EMPLOYED
50%
ROCE — PRE-FINANCING EBIT TO OPERATING CAPITAL
100%
ROE — LEVERAGED AFTER-TAX RETURN
Today's price already carries a ~20% discount to competitors — and even at a price equal to a competitor's cost the business holds a 15–25% EBITDA margin, because the process itself is cheaper.
COPPER PASSES THROUGH AT THE LME AVERAGE · CAPITAL EMPLOYED ~€4.1M PER LINEPRINCIPAL'S COPY — THE HOUSE DOES NOT CERTIFY
The Abu Dhabi Flagship — The Third Hub
KEZAD / METAL PARK · INDICATIVE USD 25–50M
Turin wrote the blueprint. Fort Wayne proved it replicates. Abu Dhabi is next.
HUB 01 · PIANEZZA, TURIN — ITALY
The blueprint plant
Group head office and R&D ecosystem. Development, validation and production of solvent-free wire on the original DryCycle® lines.
8,000 t
TARGET OUTPUT · €130M+ REVENUE POTENTIAL
HUB 02 · FORT WAYNE, INDIANA — USA
The replication
Serves US OEM and Tier 1 demand directly — customer proximity, de-risked logistics and tariffs, local supply into the largest electrification market.
~30,000 t
DESIGNED OUTPUT · €500M+ REVENUE POTENTIAL
HUB 03 · KEZAD — ABU DHABI
Built for export, anchored at home
The same modular brownfield model, at the Emirate's metals cluster. Engagement with the investment office is live, with NDA and data-room exchange under way.
Advanced-manufacturing anchor
Skilled jobs
Export earnings
Strategic-materials leadership
MODULAR BROWNFIELD SCALE-UP · 20,000 SQM PRODUCTION BASE PER HUB · 3,000 t/yr TODAY, SCALING TO 36–40,000 t/yr [CO]PRINCIPAL'S COPY
The House's Role
DOMESTIC ANCHOR · BRIDGE TO CAPITAL
TAU
The house · domestic anchor
Sovereign & institutional capital
The house represents the opportunity. It does not certify the figures — diligence does.
Market figures are drawn from cited external sources. TAU performance figures are company claims for independent verification at diligence.
Not a single deal — a position beneath the electrified economy, held at home.
Electrification is told as a story of batteries and chips. It rests equally on one hidden component. To own the layer that makes it designable is to hold a lasting industrial position in the materials of the electric age.
01
Independent diligence on TAU's company figures
02
Anchor participation in the Abu Dhabi flagship
03
A standing position in the materials of the electric age
STRICTLY PRIVATE & CONFIDENTIAL — PRINCIPAL'S COPY · NOT FOR PUBLICATION OR CIRCULATION
MARKET FIGURES ARE DRAWN FROM CITED EXTERNAL SOURCES. TAU PERFORMANCE FIGURES ARE COMPANY CLAIMS FOR INDEPENDENT VERIFICATION AT DILIGENCE. THE HOUSE REPRESENTS; IT DOES NOT CERTIFY.